Stablecoin Payments Rise as Supply Stalls: What Changes
In brief
Current as of 2026-10-19.
- Allium estimates that stablecoin payment value reached $482 billion in the first nine months of 2026, up 45% year over year, while circulating supply rose just 0.4% to about $305 billion by the end of September. CoinDesk’s report on Allium’s estimates.
- Allium counted more than one billion payments through September, but its $482 billion estimate is a filtered measure: it classified $2.4 trillion of $97.9 trillion in raw transfers as end-user activity. CoinDesk’s report on Allium’s methodology.
- Business flows and settlement pilots point to practical use, while card spending remains a small share of conventional network volume and bank liquidity remains a key dependency. Allium’s September report, New York Fed staff report.
What changed
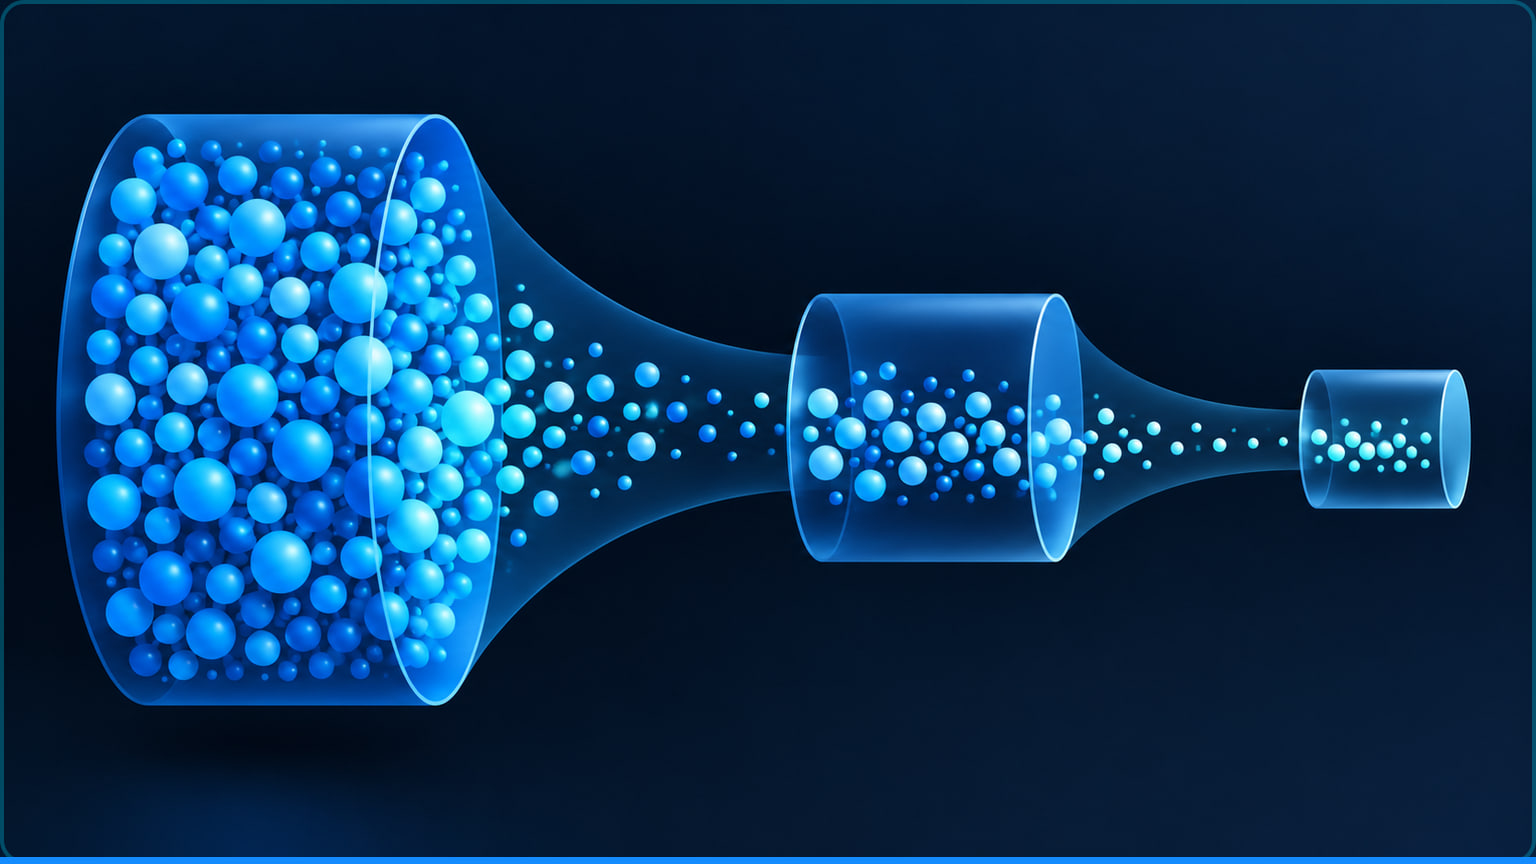
Stablecoin payment activity grew faster than circulating supply in the first nine months of 2026. Allium estimated payment value at $482 billion, up 45% year over year, while supply stood at about $305 billion at the end of September, just 0.4% above the start of the year. The payment count rose 71% to more than one billion. Taken together, these measures suggest that the stablecoins already in circulation were used more frequently for payments; they do not, by themselves, show how much activity represents persistent business demand. CoinDesk’s report on Allium’s estimates.
The measurement method matters. Allium’s estimate starts with $97.9 trillion in raw transfers through September, then removes exchange, decentralized finance, and automated transfers. It classified $2.4 trillion as end-user activity, from which the $482 billion payment estimate was derived. Raw on-chain volume, adjusted end-user activity, and payments are therefore distinct measures; citing raw transfers alone would overstate the scale of payments. CoinDesk’s report on Allium’s methodology.
The filtered data show signs of business use. Allium’s September report estimated that businesses received 58%–64% of stablecoin payment volume, with business-to-business settlement accounting for $137–153 billion. Yet 61% of geographically attributed payment volume remained domestic. This finding tempers the idea that payment growth is chiefly evidence of cross-border commerce: business use may include domestic operations as well as international settlement. Allium’s September report.
Why it matters
The evidence supports a measured conclusion: stablecoins are seeing increased payment activity, including business flows, but activity growth alone does not establish durable, broad adoption. Card spending illustrates the difference between a fast growth rate and meaningful scale. Allium measured $3.9 billion in stablecoin-linked card spending through September, ten times the year-earlier level; CoinDesk reported that this represented 0.03% of Visa’s $4 trillion in second-quarter payment volume. The growth is notable, but the comparison base remains small. CoinDesk’s report on card spending.
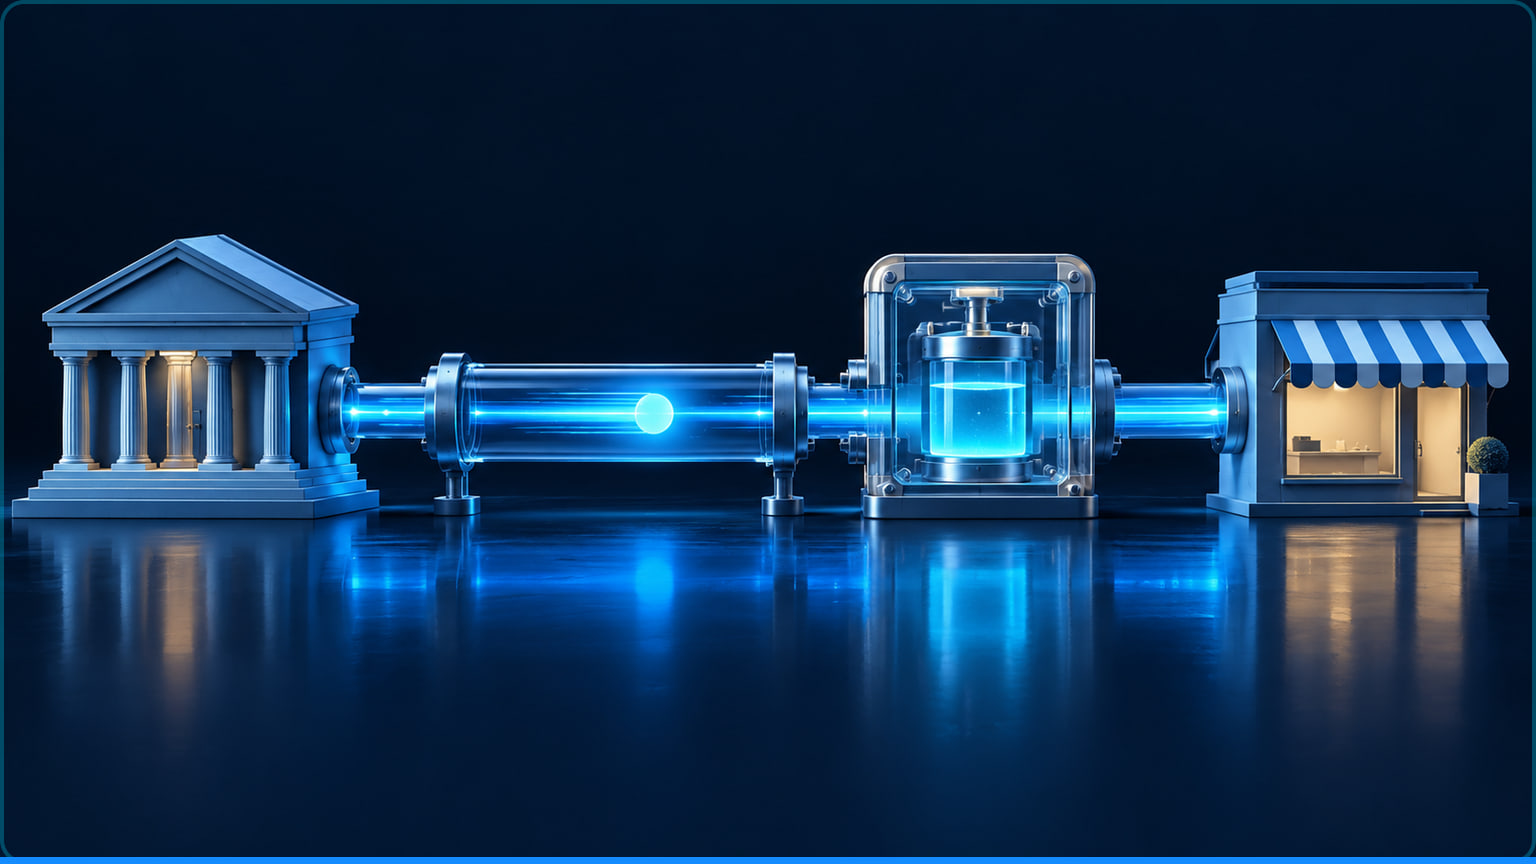
For finance and product teams, a useful test is whether stablecoin settlement solves a specific operational problem after accounting for the full payment path. A faster transfer on a blockchain may still depend on issuer redemption, liquidity at the point of conversion, access to banking services, and local payout rails. The available figures establish payment activity; they do not show that every transfer can be redeemed or paid out on the same terms in every market. These dependencies should be assessed as part of a deployment, rather than inferred from aggregate transaction growth.
A pilot offers a concrete example of the distinction between settlement testing and a consumer launch. In a seven-day pilot with Visa, Lloyds used USDC purchased through the UK-regulated exchange Archax to settle $750,000 in payment obligations. Visa received the funds in under an hour, including over a weekend. Lloyds described the work as a settlement test alongside existing processes. It demonstrates one tested route under specific conditions; it does not establish that the route is available to all customers or in all geographies. Lloyds and Visa’s pilot announcement.
Banks are also part of the liquidity picture. A New York Fed staff report finds that banks holding stablecoin deposits face increased payment demand and liquidity exposure linked to primary-market activity. It also finds that these banks maintain larger reserve balances to mitigate potential shortfalls. For treasury teams and banking partners, this points to an operational dependency: stablecoin activity can affect liquidity management at the institutions that support it. New York Fed staff report, “Stablecoin Disintermediation”.
IT Finance perspective: what this means in practice
For implementation teams, the relevant question is not whether activity is rising, but whether a proposed payment flow can reliably meet a defined business need, from funding through final payout. That means mapping each point where a bank, issuer, exchange, payment provider, or local rail is required, and identifying what happens when one of those dependencies is unavailable. The reported pilot and aggregate payment estimates show different things: one tests a specific settlement route, while the other measures activity across a broader set of flows.
Decision-makers should separate three claims when assessing a business case: that stablecoin transfers are occurring, that businesses account for a substantial share of measured payment volume, and that a particular company can operate a repeatable flow in its target markets. The first two are supported by Allium’s estimates. The third requires evidence about the company’s own counterparties, redemption path, liquidity arrangements, and payout access. Results from one pilot should not be treated as proof that those conditions hold elsewhere.
Interoperability also deserves explicit review. A flow may cross blockchain and conventional settlement systems, so teams should determine how transactions are reconciled across those systems and how exceptions are handled. This is a practical risk assessment, not a claim that current deployments share a single technical design. If your team is evaluating a stablecoin settlement flow, IT Finance’s blockchain integration services can help assess the architecture, dependencies, and operational requirements.
What to do next
- Define the payment problem first: identify the corridor, counterparties, payout method, and operational constraint the stablecoin flow is intended to address.
- Map funding, redemption, and payout dependencies with the relevant banking and payment partners, including how liquidity and exceptions will be handled.
- Evaluate activity using clear definitions: distinguish raw transfers from filtered end-user activity, and track business flows separately from card spending.
- Treat a pilot as evidence for the route and conditions tested. Before scaling, confirm that the necessary counterparties and rails are available for the intended use.
Conclusion
Stablecoin payment activity rose while supply remained nearly flat, and Allium’s estimates point to meaningful business participation. But the evidence does not establish broad, durable adoption on its own: adjusted payment activity is a filtered measure, card spending remains a small share of conventional network volume, and settlement depends on liquidity and access to financial infrastructure. Business decisions should rest on a tested payment path and its dependencies, not on transaction growth alone.
FAQ
Does rising payment activity prove durable business adoption?
No. The reported growth and Allium’s estimate of business payment share are evidence of activity, but aggregate figures do not prove that a particular company can sustain a repeatable flow in its markets.
Why does flat stablecoin supply matter?
It shows that payment activity rose without a comparable increase in circulating supply over the period measured. That may indicate more frequent use of existing supply, but supply and payment activity alone do not establish why the flows occurred or whether they will persist.
What should a business validate before using stablecoin settlement?
It should assess the specific funding, redemption, liquidity, banking, and payout dependencies for its intended flow. A pilot can inform that assessment, but its results apply to the route and conditions tested.
Sources
- CoinDesk: Stablecoin supply stalls, but payments jump 45% as Visa, Mastercard and Stripe connect crypto to cash
- Allium: State of Stablecoins and Payments: September 2026
- Lloyds Banking Group: Lloyds and Visa test faster, round-the-clock cross-border settlement using stablecoins
- Federal Reserve Bank of New York: Stablecoin Disintermediation
This article was prepared with the support of AI tools and verified against the public sources listed above.